Guides
How to Set a Marketing Budget Using Revenue and Margin
A revenue percentage can hide a spending plan your business cannot afford. Learn how to use contribution margin, profit targets and cash flow to set a practical limit, with a worked example in Indian rupees.
On this page
- Overview
- Start with the right revenue and margin figures
- Calculate your marketing budget from available contribution
- Separate baseline spending from growth-funded investment
- Check cash flow before committing expenditure
- Turn the ceiling into an all-in spending plan
- Use customer economics to judge additional investment
- Review the plan using evidence, not just expenditure
- Frequently asked questions
- Decide what deserves funding before spending more
Overview
A marketing budget should start with what your business can afford to invest, not a percentage copied from another company. Revenue tells you the size of the business, but margin tells you how much of that revenue is available to fund growth, cover overheads and generate profit.
The practical approach is to calculate an affordable spending ceiling, check whether cash flow supports it and then decide which work deserves funding. The worked example below uses Indian rupees and separates spending supported by current trading from additional investment that depends on growth.
Start with the right revenue and margin figures
### Use net revenue, not headline turnover
Choose a planning period, usually the next financial year, supported by a monthly forecast. Start with net revenue after discounts, refunds and returns. Exclude GST or other taxes collected on behalf of the government.
For subscription businesses, use revenue recognised during the period rather than treating the full value of a multiyear contract as current revenue. Track bookings and collections separately because they answer different questions.
Build the forecast from current trading, customer retention, seasonality and realistic sales assumptions. A target chosen to satisfy an ambitious growth plan is not yet a dependable funding source.
### Distinguish gross margin from contribution margin
**Gross margin** is revenue less cost of goods sold, expressed as a percentage of revenue. It is a useful starting point, but it may leave out costs that increase with each sale.
For budgeting, calculate **contribution margin before marketing**. Deduct product or delivery costs and other variable operating costs, such as payment processing, fulfilment, sales commissions and transaction-linked support, where applicable. Avoid deducting any cost twice if it is already included in cost of goods sold.
A marketing budget based on gross margin alone can overstate affordability when these additional costs are substantial.
For example, a product selling for ₹10,000 might have ₹5,000 in product costs and another ₹1,000 in variable operating costs. Its gross margin is 50%, but its contribution margin before marketing is only 40%.
Use a consistent definition throughout the plan. Marketing costs belong in the spending envelope calculated below, not in both the contribution calculation and that envelope.
Calculate your marketing budget from available contribution
Once the revenue and margin definitions are clear, calculate the amount left after non-marketing overheads and your required operating profit.
**Contribution before marketing = Net revenue × Contribution margin before marketing**
**Maximum marketing spend = Contribution before marketing − Non-marketing fixed operating costs − Required operating profit**
The operating profit target here is before interest and tax. If debt repayments, tax payments or other cash commitments restrict spending, account for them in the separate cash-flow check.
This formula produces an affordability ceiling, not a recommendation to spend every available rupee. The right investment may be lower if the business lacks a worthwhile opportunity or the capacity to execute it.
### Worked example: a business with ₹1 crore in revenue
Assume the following figures for the coming year. All amounts are illustrative, not industry benchmarks.
| Planning input | Annual amount | |---|---:| | Net revenue | ₹1,00,00,000 | | Contribution margin before marketing | 40% | | Contribution before marketing | ₹40,00,000 | | Non-marketing fixed operating costs | ₹25,00,000 | | Required operating profit | ₹10,00,000 | | Maximum marketing spend | ₹5,00,000 |
The calculation is ₹40,00,000 minus ₹25,00,000 minus ₹10,00,000, leaving ₹5,00,000.
That happens to equal 5% of revenue. But **5% is the output of this business’s economics, not a rule applied at the start**.
The ₹25,00,000 overhead figure must exclude costs assigned to marketing. If marketing salaries are already included there, move them into the marketing cost calculation or adjust the formula consistently. Otherwise, the marketing budget will count the same expense twice.
### Stress-test the assumptions before approving spending
Small changes in revenue or margin can materially change the available amount.
| Scenario | Net revenue | Contribution margin | Spending ceiling after the same overheads and profit target | |---|---:|---:|---:| | Base case | ₹1,00,00,000 | 40% | ₹5,00,000 | | Lower revenue | ₹90,00,000 | 40% | ₹1,00,000 | | Lower margin | ₹1,00,00,000 | 35% | ₹0 |
In the lower-margin case, the business can meet its stated profit target before marketing, but has no remaining room for marketing expenditure.
That does not mean stopping every activity is automatically the right decision. It means the assumptions cannot all hold simultaneously. Management must reconsider costs, pricing, the profit target or an explicitly funded investment plan rather than hiding the shortfall behind an arbitrary percentage.
Separate baseline spending from growth-funded investment
A forecast can become circular: marketing expenditure is justified by higher revenue, while higher revenue is justified by the proposed expenditure.
Avoid this by separating two funding levels. The **baseline allowance** uses revenue supported by current trading and a realistic retention forecast. A **conditional growth allowance** depends on additional revenue and contribution that have not yet been established.
In the example, the baseline marketing budget is ₹5,00,000. Suppose a proposed expansion could produce another ₹20,00,000 in net revenue at the same 40% contribution margin. That would add ₹8,00,000 in contribution before marketing.
If non-marketing fixed costs and the profit target remain unchanged, the total annual ceiling could rise to ₹13,00,000. However, the additional ₹8,00,000 is conditional, not automatically available on day one.
Release it in stages as evidence improves. If the expansion requires extra staff, facilities or service capacity, subtract those additional costs first.
The baseline is also a forecast, so test its downside. The distinction is between spending supported by stronger evidence and spending dependent on a new growth assumption, not between guaranteed and uncertain revenue.
Check cash flow before committing expenditure
An affordable marketing budget on an annual profit forecast can still create a cash shortage. Customers may pay late, inventory may require payment upfront and annual software or agency commitments may fall due before the associated revenue arrives.
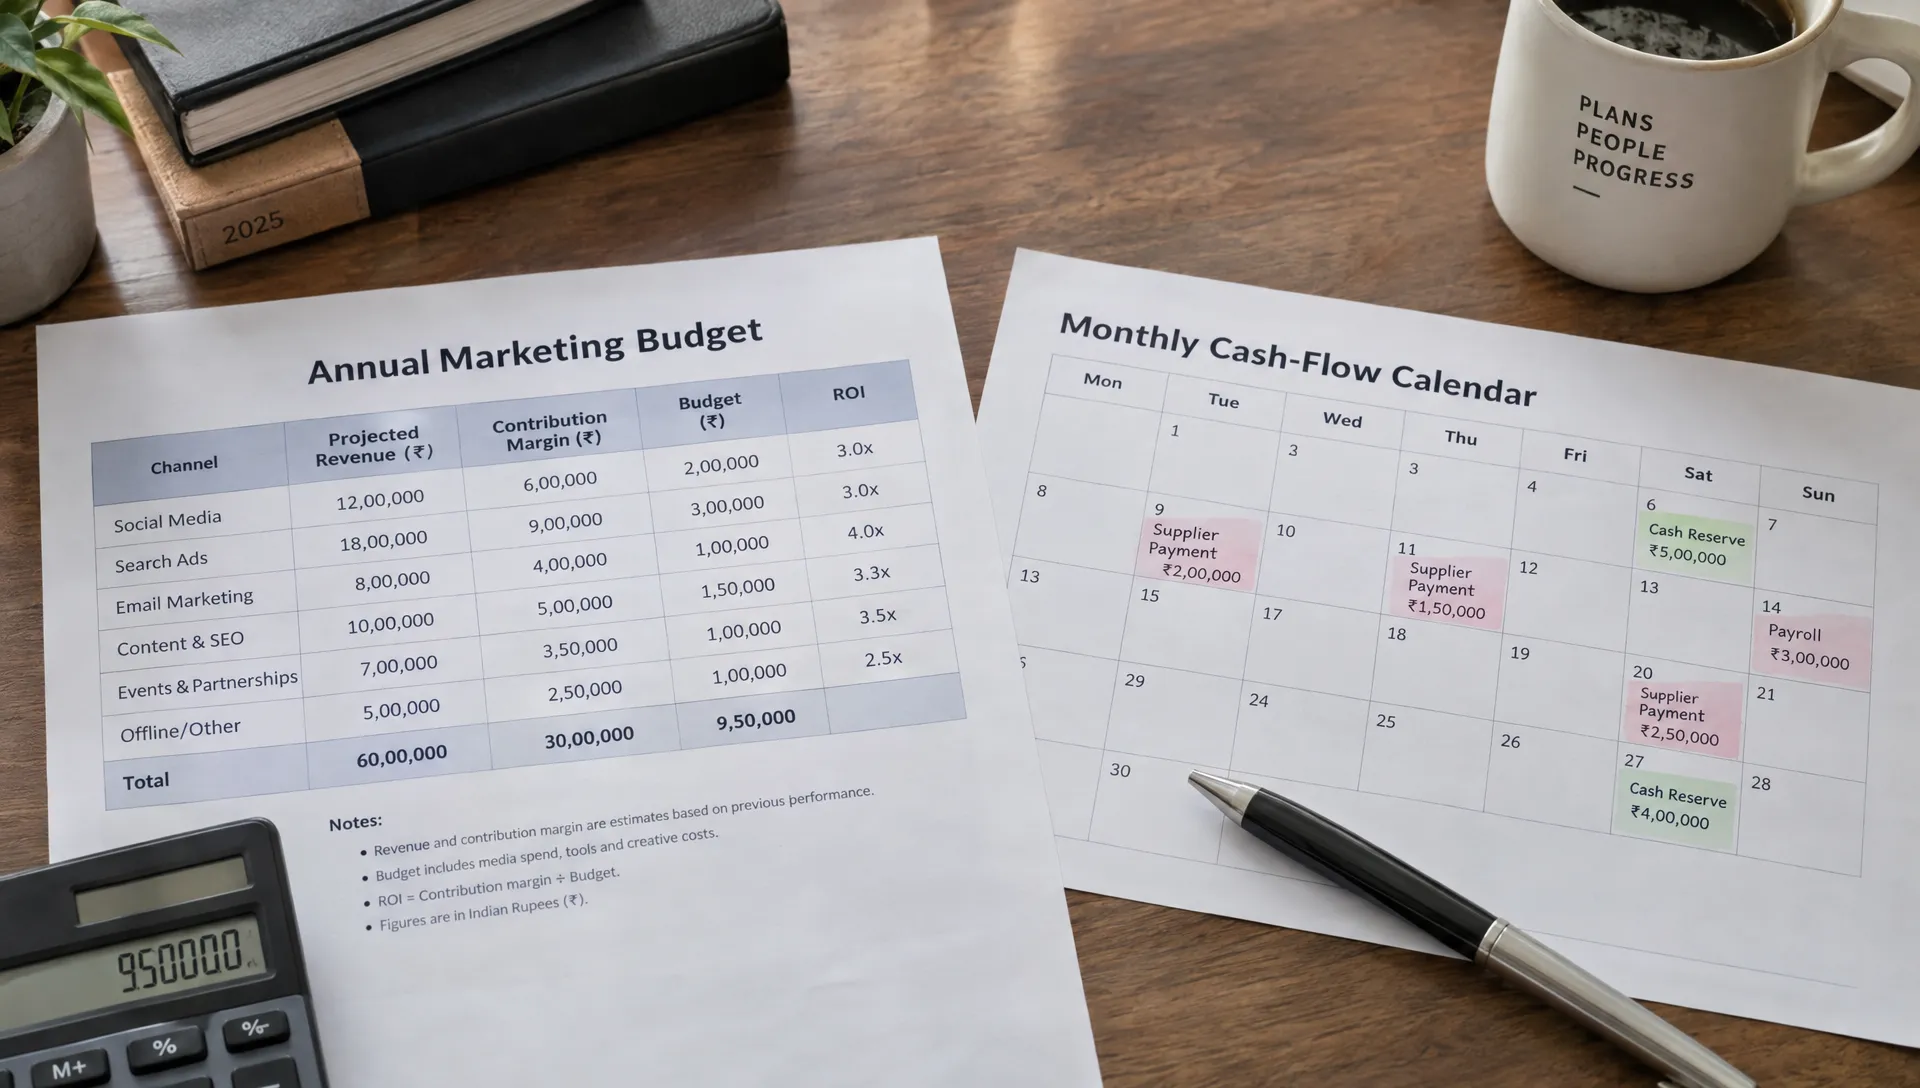
Build a monthly cash forecast that includes collections, supplier payments, payroll, taxes, debt commitments and the business’s required cash reserve. Then insert the proposed marketing payment schedule.
For example, dividing ₹5,00,000 into four equal quarters gives ₹1,25,000 per quarter. If the first quarter has only ₹80,000 available after other commitments and the reserve, an equal allocation is not cash-supported.
You would need to change the timing, reduce commitments or secure approved funding. Revenue seasonality may also justify uneven spending, but only where both demand and cash availability support it.
Keep the operating reserve separate from money available for discretionary growth. A positive annual profit forecast does not remove the risk of running out of cash during the year.
Turn the ceiling into an all-in spending plan
The spending envelope must cover more than advertising. Include marketing staff costs, agency or specialist fees, creative production, content, software, research and relevant website or conversion work. Record existing contractual commitments before allocating anything new.
An illustrative allocation of the ₹5,00,000 ceiling might look like this:
| Cost category | Annual allocation | |---|---:| | Paid media | ₹1,60,000 | | Marketing people and external support | ₹1,50,000 | | Creative, content and conversion work | ₹90,000 | | Analytics and marketing tools | ₹40,000 | | Uncommitted testing reserve | ₹60,000 | | Total | ₹5,00,000 |
These amounts demonstrate how to reconcile the total, not how every business should divide its spending. Assign each cost once. When reserve money is approved for an experiment, transfer it to the relevant category rather than adding it on top.
**Allocate against the growth constraint, not a standard channel mix.** If qualified demand exists but enquiries fail to convert, improving the offer or sales journey may deserve funding before more traffic. If contribution margin is weak, pricing or product economics may need attention first.
A marketing budget is useful only when its line items connect to a commercial purpose. Give each significant allocation an owner, a cost estimate and an outcome that can be assessed, while allowing longer-term work an appropriate measurement window.
Use customer economics to judge additional investment
The annual ceiling answers whether the business can afford the plan. Customer economics help answer whether a particular growth investment is worthwhile.
Suppose a new customer generates ₹10,000 in net revenue from their first purchase, with a 40% contribution margin before marketing. That produces ₹4,000 in contribution.
If the fully loaded acquisition cost is ₹2,500, the first purchase leaves ₹1,500 towards fixed overheads and operating profit. That may be attractive, but it does not independently prove that the whole annual plan meets the profit target.
Track the relevant measures together:
- **Fully loaded customer acquisition cost:** Include the acquisition-related costs being assessed, not just platform spend, and keep the definition consistent. - **Contribution after acquisition:** Measure what remains after variable operating costs and the relevant acquisition costs. - **Payback period:** Estimate how long customer contribution takes to recover acquisition spending, then compare that timing with cash capacity.
At a 40% contribution margin, media-only break-even return on ad spend is 2.5 times net revenue per rupee of advertising spend, before other marketing costs and fixed overheads. It is a break-even reference, not a sufficient profit target.
Your marketing budget should therefore respond to contribution and payback, not platform ROAS alone. As BizFay explains, [acquisition cost is not always the underlying problem](https://bizfay.com/blogs/your-acquisition-cost-isnt-always-the-problem); weak economics or conversion can change what the same acquisition spend delivers.
Treat repeat purchases as upside until retention data supports them. Forecast lifetime value is not cash available today.
Review the plan using evidence, not just expenditure
Review performance monthly and reconsider the full-year forecast quarterly, or sooner if revenue, margin or cash conditions change materially.
Compare actual net revenue, contribution margin, cash collections and committed costs with the assumptions used at approval. Recalculate the remaining spending capacity using an updated full-year forecast, including money already spent and obligations that cannot easily be cancelled.
Being under the spending ceiling is not evidence that the work is effective. Equally, a campaign missing an early target does not always justify cancelling it before enough data has accumulated.
Before releasing conditional funding, define what the next investment must demonstrate. BizFay’s discussion of [the decisions made before a campaign starts](https://bizfay.com/blogs/the-most-expensive-marketing-decision) is relevant here: the approval should specify what the business needs to learn, not merely what it will launch.
Scale a marketing budget when additional spending has a credible path to incremental contribution and acceptable cash recovery. Where practical, use holdouts or other controlled tests to distinguish additional sales from sales that would have happened anyway. Platform-attributed revenue alone does not establish that distinction.
If the economics weaken, reduce uncommitted expenditure first. Protect work that is demonstrably useful rather than cutting every category by the same percentage.
Frequently asked questions
**What percentage of revenue should a business spend on marketing?** There is no universal percentage. Calculate available contribution after non-marketing overheads and the required operating profit, then check cash flow. Express the resulting amount as a revenue percentage for reporting and comparison, not as the original justification.
**Should salaries and agency fees be included?** Yes, when assessing total marketing expenditure. Include relevant staff costs, external support, tools and production as well as advertising. Ensure those same expenses are not also deducted as non-marketing overheads.
**What if the business is deliberately investing at a loss?** Replace the positive profit requirement with an explicitly approved loss limit. Check available funding, cash runway and the milestones that would justify continued investment. A negative-profit plan needs financing and oversight, not just a higher revenue percentage.
**How often should a marketing budget change?** Review actual performance monthly and update the broader plan quarterly. Reassess sooner when margins fall, collections slow or new evidence changes the expected contribution from an investment. Avoid changing direction solely because of short-term advertising fluctuations.
Decide what deserves funding before spending more
A revenue-and-margin calculation gives you a financial boundary. Choosing the work inside that boundary requires a diagnosis of what is holding growth back.
[BizFay](https://bizfay.com) combines growth strategy, business analysis, marketing execution and measurement to help businesses prioritise the investments they actually need. Start with the commercial constraint, then fund work that can address it.
Was this useful?
Related blogs
Guides
7 Marketing Objectives That Connect Activity to Revenue
Busy campaigns do not guarantee profitable growth. These seven objectives show how to connect demand, conversion and retention to revenue, choose useful measures and decide which marketing investment deserves attention first.
Guides
How to Build a Marketing Strategy Around Your Best Customers
Your biggest accounts are not always your best customers. Learn how to identify profitable relationships, understand what drives purchases and use that evidence to focus your marketing budget on growth worth pursuing.
Related insights
Framework
The cost of answering the wrong question
Most underperforming growth programmes are executed well. They are simply answering a question the business did not need answered. A working method for finding the real one.
Analysis
Acquisition cost is a symptom, not a diagnosis
Rising CAC is usually treated as a media problem. Broken down properly, it is often an offer, margin or conversion problem wearing a media costume.
Newsletter
Get new BizFay thinking by email
New blogs and insights on growth decisions, when we publish them.